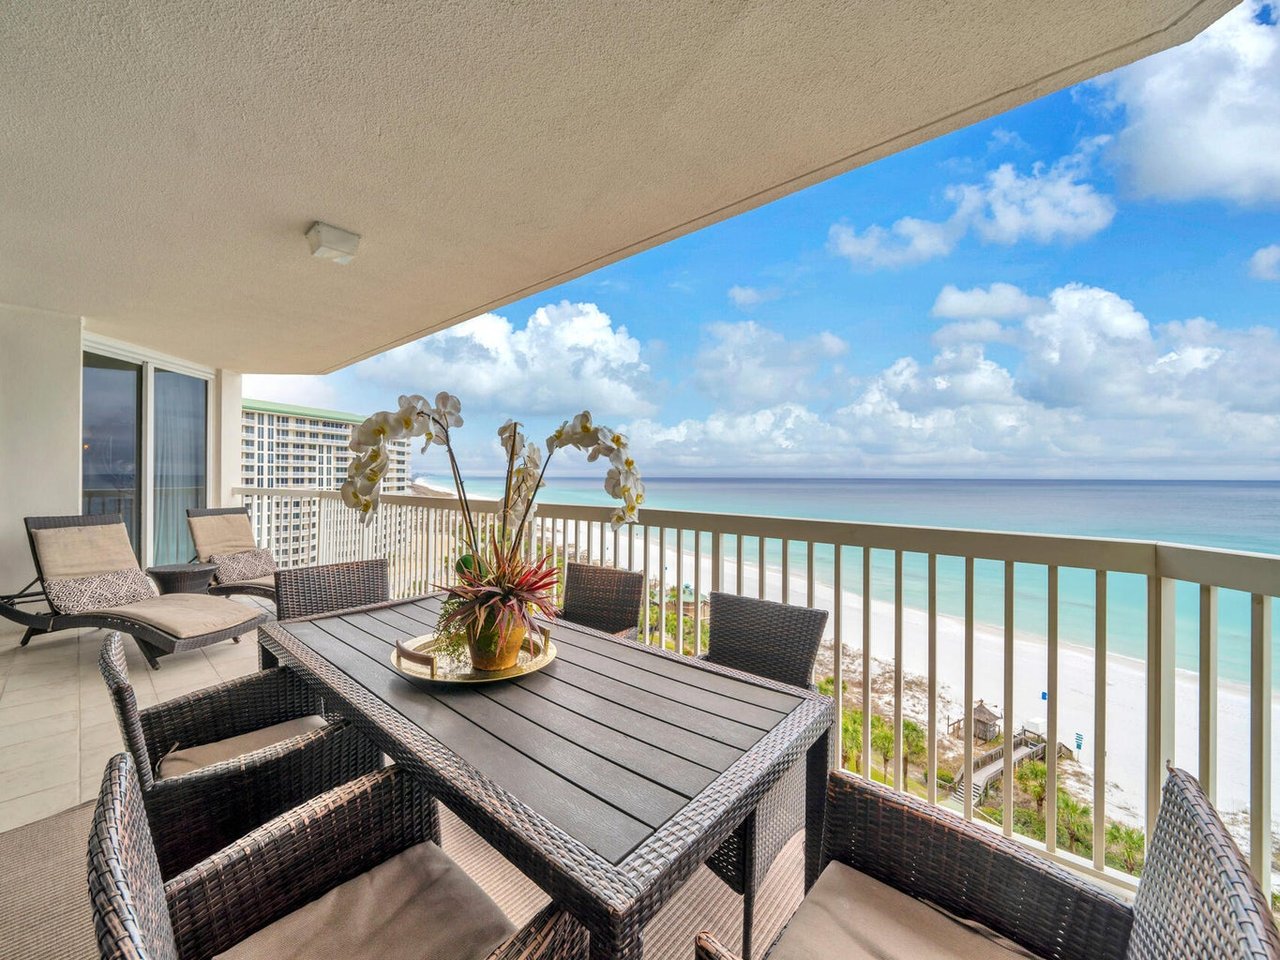
Buying a Condo on the Florida Coast? 10 Things to Know Before You Buy
30A Angela Skillingstad August 17, 2026
30A Angela Skillingstad August 17, 2026
To search properties simply remember J30A.com.
Buying a condo on the Florida coast can be a smart way to own a second home, a lock-and-leave beach escape, or a carefully planned investment. It is also a different purchase than a freestanding house. You are buying the unit and a share of the association’s building, reserves, rules, and culture.
From The Jonathan Hill Team at Legacy Hill Real Estate — with Angela Skillingstad often helping clients work through condo questionnaires and association packets along 30A, Santa Rosa Beach, Destin, and Miramar Beach — here are ten things to know before you buy. This checklist is written for this corridor, not generic Florida brochure advice.
Coastal condo living is not one market:
Start with how you want a Tuesday in October to feel, then pick geography. Our Santa Rosa Beach neighborhood guide helps frame the west-end living map before you fall in love with a balcony view alone.
Do not judge a condo only by the monthly association fee amount you see on a listing. One association may include master building insurance, water, cable, internet, pest control, pool service, and landscaping. Another may include far less. The better question is: What am I getting for it, and what will I still write checks for?
Request a current budget and fee schedule in writing. Compare inclusions side by side when you are deciding between a 30A-address condo and a Destin mid-rise that looks cheaper at first glance.
Ask whether any special assessments are underway or reasonably anticipated, and whether the seller has paid their share. Roofs, elevators, exterior restoration, structural repairs, and seawall or building-envelope projects can create large owner obligations. Surprise assessments are one of the fastest ways an out-of-state buyer feels burned.
Your contract contingencies and association estoppel should surface known amounts. Still ask verbally. Paper and hallway rumors both deserve follow-up.
Review the association’s financial statements, reserve study materials (when available), and budget trends. Healthy reserves do not guarantee a perfect building — but thin reserves raise the odds of sudden owner bills. Coastal buildings live hard lives: sun, salt, wind, and heavy guest traffic in some towers.
If the packet is incomplete, slow down. A beautiful kitchen remodel inside the unit does not fund the roof.
Florida condo insurance typically has two layers: the association’s master policy and the owner’s HO-6 (or equivalent) policy for interior coverage and personal obligations. Understand what the master policy covers, what deductibles look like at the association level, and what you must insure yourself.
Start insurance conversations early — especially for coastal wind and flood realities. We will not invent premium numbers here because quotes are property- and buyer-specific. Get actual quotes while your inspection and association review are underway, not the week of closing.
If you might rent — even occasionally — read the documents. Some associations allow short-term vacation rentals; others require minimum lease terms or limit frequency. Walton County registration and state tax / licensing steps may also apply depending on product type and use pattern. County materials have noted nuances for certain condominiums versus other dwelling types — confirm current rules rather than assuming a neighbor’s setup transfers to you.
Even if you do not plan to rent now, rental rules affect your future options and the buyer pool when you sell. For corridor-wide eligibility thinking, see Can you short-term rent in any 30A neighborhood?
If income matters, ask for actual rental history when available — calendars, statements, or manager reports — and treat marketing projections as marketing. Methods differ. Seasonality on this coast is real. Your personal-use weeks reduce available guest weeks. Underwrite cautiously and keep lifestyle fit first unless you are explicitly buying an income product.
Balcony photos sell dreams. Access and parking sell weeks:
Walk the access at a busy hour when you can. Owners miss this in online photos constantly.
Association living includes rules that affect real life: pet weight or breed policies, hard-surface flooring approvals, balcony decor limits, construction hours, and guest registration procedures. If you are coming from a freestanding Santa Rosa Beach home, the adjustment can be bigger than you expect — sometimes happily so (less exterior maintenance), sometimes not (less autonomy).
Read the rules before you customize a renovation fantasy.
A clean sequence protects you:
Special-assessment red flags, thin reserves, unresolved building litigation mentions in minutes, or rental-rule surprises should pause the process until understood. Price alone is not value.
This guide is for primary second-home buyers, remote closers, and careful investors who want Northwest Florida condo ownership without wishful underwriting. It is intentionally corridor-specific: Santa Rosa Beach and 30A for lifestyle adjacency to the Scenic Highway towns; Destin and Miramar Beach when elevator convenience and certain mid-rise amenities matter more. If a building’s story only works with aggressive income assumptions, we will say so and redirect you to a better-fit product — sometimes a freestanding home, sometimes a different association entirely.
A lower asking price can lose to fees, insurance reality, assessments, and rental limits. A higher-fee building can be the better ownership experience if reserves are healthier and inclusions are stronger. Look at the whole picture.
If you are comparing condo options along 30A, Santa Rosa Beach, Destin, or Miramar Beach, we will help you ask the document questions in the right order. Search on J30A.com, then reach The Jonathan Hill Team at Legacy Hill Real Estate — 495 Grand Blvd Suite 206, Miramar Beach, FL 32550 · (205) 370-5905 · Broker Jonathan Hill, FL BK3323086.
Related: Santa Rosa Beach neighborhood guide · 30A & Santa Rosa Beach FAQ · 30A realtor · Santa Rosa Beach realtor.
Stay up to date on the latest real estate trends.
Watersound Beach vs Origins: Gulf-front gated Beach vs inland Lake Powell Origins — rental rules, club, and how to search without blending the brand.
What WaterColor buyers should verify in the community’s short-term rental portal before planning for rental income or longer stays.
Indaco brings a weeknight dining option next to O-Ku in Alys Beach, adding another reason to enjoy the town center after dark.
What Rosemary Beach buyers should know about Florida HOA transfer fees, current rules, and questions to ask before making an offer.
When the Rosemary Beach concert calendar goes quiet, the town still fills with dinner walks, town-center evenings, and a buyer calendar that does not run on festival w… Read more
30A
Why interactive property walkthroughs help out-of-town buyers evaluate homes on 30A before they can visit in person.
Watersound is one brand covering Beach, Bridges, Origins, Camp Creek, and more — prices and rental rules are not interchangeable.
30A
From HOA fees and insurance to assessments, rental restrictions, and beach access, here’s what every Florida condo buyer should consider before purchasing.
A resident’s look at how WaterColor’s week kept moving with pool time, dining, and summer activities beyond the pickleball courts.
Looking for expert advice in the 30A real estate market? The Jonathan Hill Team is ready to provide you with the insight and expertise you deserve.